Can a partnership use a partner's SSN?
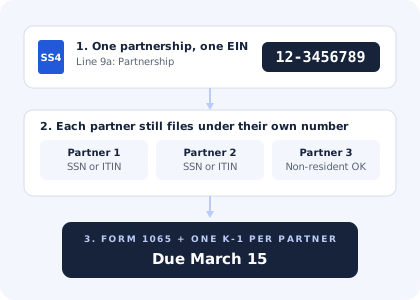
No. A partner SSN is rejected on Form 1065, on the K-1 set, and at the bank. 2 partners means 1 partnership EIN plus 2 individual numbers, and the 3 identifiers do 3 different jobs on the return.
The partnership reports income at the entity level and passes it through on the K-1s. Each partner then reports that share under their own SSN or ITIN. Mixing the two produces a mismatch the IRS flags against the partner rather than the partnership. The distinction is drawn on EIN vs SSN.
This is the sharpest contrast with a sole proprietorship, where a solo operator with 0 employees keeps using an SSN. The single-owner rules sit on EIN for a sole proprietorship.
How do you apply for a partnership EIN?
5 steps, about 11 minutes of form work. Put the agreement in writing, name 1 general partner as responsible party, check Partnership on line 9a, complete the operating fields, then sign and send.
Which SS-4 lines does a partnership answer?
8 lines carry the weight. Line 9a takes the Partnership box, line 7a names 1 general partner as responsible party, and line 13 takes a number in all 3 employee boxes, including 0.
Line 1 — Legal name of entity
Enter the name on the partnership agreement, or the name the state approved for an LP, LLP, or multi-member LLC.
A general partnership with no state filing uses the name on its written agreement. That name prints on the CP-575 and on every K-1.
Line 4a and 4b — Mailing address
The IRS mails the CP-575 confirmation letter here. Line 4b takes city, state, and ZIP code.
The IRS accepts a foreign mailing address, which matters when every partner sits outside the US.
Line 7a and 7b — Responsible party
Line 7a names 1 general partner who controls the partnership and its funds. Line 7b takes that person's SSN or ITIN, and the word Foreign when the person holds neither.
The responsible party is 1 individual, never the partnership and never the partner group. An entity on line 7a triggers rejection.
Line 8a and 8b — LLC question
A multi-member LLC answers Yes and enters its member count on line 8b. A general partnership, LP, or LLP answers No.
Answering Yes with 2 or more members and Partnership on line 9a is the standard multi-member LLC combination.
Line 9a — Type of entity
Check the Partnership box.
This is the field that opens the Form 1065 account. Checking Corporation instead makes the IRS expect a return the partnership never files.
Line 11 — Date the business started
Enter the date the partnership agreement took effect, in month, day, year order.
For an LP, LLP, or multi-member LLC this is the state approval date rather than the handshake date.
Line 12 — Closing month of accounting year
Enter December for a calendar-year partnership, which sets the Form 1065 deadline at March 15.
A partnership takes the tax year of its majority partners under IRC section 706, unless it establishes a business purpose for another. Changing it later takes Form 1128.
Line 13 — Highest number of employees expected
Enter a number in all 3 boxes: agricultural, household, and other. Enter 0 in each box where none apply.
Partners are not employees. A partner drawing guaranteed payments does not count in these boxes.
Every field on the form appears on the Form SS-4 walkthrough.
Which partnership types need an EIN?
All 5 forms need 1 EIN each: general partnership, limited partnership, limited liability partnership, limited liability limited partnership, and a multi-member LLC taxed as a partnership.
| Structure | Needs EIN? | Default return |
|---|---|---|
| General partnership | Yes | Form 1065 |
| Limited partnership | Yes | Form 1065 |
| Limited liability partnership | Yes | Form 1065 |
| Multi-member LLC (default) | Yes | Form 1065 |
| Joint venture, 2 spouses | Depends on election | Form 1065 or 2 Schedule Cs |
Source: IRS Instructions for Form SS-4 and Form 1065.
A qualified joint venture is the 1 narrow exception. 2 spouses who jointly own and operate an unincorporated business in a non-community-property state can elect out of partnership treatment and file 2 Schedule Cs instead.
Does a multi-member LLC count as a partnership?
Yes, by default. An LLC with 2 or more members is taxed as a partnership and files Form 1065 unless it elects otherwise. Line 8a takes Yes with the member count, and line 9a takes the Partnership box.
Electing corporate treatment instead takes Form 8832, and that election locks the classification for 60 months under 26 CFR § 301.7701-3(c)(1)(iv). The default rule itself sits in 26 CFR § 301.7701-3(b)(1). Member-count mechanics are covered on EIN for an LLC.
What does a partnership file each year?
Form 1065 by March 15, the 15th day of the 3rd month after the year closes, plus 1 Schedule K-1 per partner by the same date. A 6-month extension moves the return to September 15.
| Filing | Who receives it | Deadline |
|---|---|---|
| Form 1065 | IRS | March 15 |
| Schedule K-1 | Each partner | March 15 |
| Form 7004 (extension) | IRS | March 15, extends to September 15 |
| Form 941 (with payroll) | IRS | April 30, July 31, October 31, January 31 |
A general partner's distributive share carries self-employment tax at 15.3 percent, split 12.4 percent Social Security and 2.9 percent Medicare. Guaranteed payments carry it as well, and both are reported through the K-1 rather than a W-2.
When does a partnership need a new EIN?
3 events force a new number: incorporating the partnership, 1 partner buying out the rest and continuing alone, or closing 1 partnership and opening another. A name change forces 0, and a move forces 0.
Adding or removing a partner while the partnership continues keeps the same 9-digit number. A change of responsible party is reported on Form 8822-B within 60 days, and the EIN itself never changes. The account-closure route is set out on cancelling an EIN.
The statutory frame sits in 4 places. IRC section 6031 requires the return itself. Section 708 sets when a partnership terminates for tax purposes. Section 761 lets certain investing and joint-production groups elect out of subchapter K. Form 8832 elects corporate treatment instead, and Form 1128 changes the accounting year on line 12 of the 18-line SS-4.
How do non-US partners apply?
By fax or mail, with Foreign written on line 7b. A partnership accepts non-resident partners, unlike an S corporation, which permits 0. The IRS online tool requires an SSN or ITIN and rejects the rest.
Fax Form SS-4 to 855-215-1627 from outside the US and the EIN returns in 4 to 7 business days. Income effectively connected with a US trade or business and allocated to a foreign partner carries section 1446 withholding, at 21 percent for corporate partners. Country-level detail sits on EIN by country.
How long does it take and what does it cost?
15 minutes online with an SSN or ITIN. 4 to 7 business days by fax to 855-641-6935. 6 to 11 weeks by mail. The IRS fee is $0 on every route, and the number never renews.
| Route | Turnaround | IRS fee |
|---|---|---|
| Online at irs.gov | 15 minutes | $0 |
| Fax | 4 to 7 business days | $0 |
| 6 to 11 weeks | $0 | |
| einnumber.co | 5 business days, or 24 hours on Fast | $67 or $97 |
Channel timings sit on how long an EIN takes, and the price comparison on what an EIN costs.